India’s data center industry is expanding rapidly, transitioning from a niche IT function to a vital strategic asset. Driven by data localization mandates (such as the Digital Personal Data Protection Act of 2023) and extensive government incentives, operational capacity reached 1.5 GW by mid-2025 and is projected to hit 9 GW by 2032.
The sector has drawn massive foreign direct investment (FDI), attracting roughly $60 billion between 2019 and 2024. Key metropolitan hubs include:
Mumbai/Navi Mumbai: Represents 53% of national capacity.
Chennai: Holds a 21% market share and hosts AI-ready hubs.
Noida: Serves as North India’s primary processing node.
With construction costs 30-40% cheaper than in the US or UK, global tech giants like Amazon Web Services and Google are investing heavily. Every 1 GW of new capacity generates $4-6 billion in ecosystem expenditure, creating advanced technical jobs and fueling India’s digital economy.
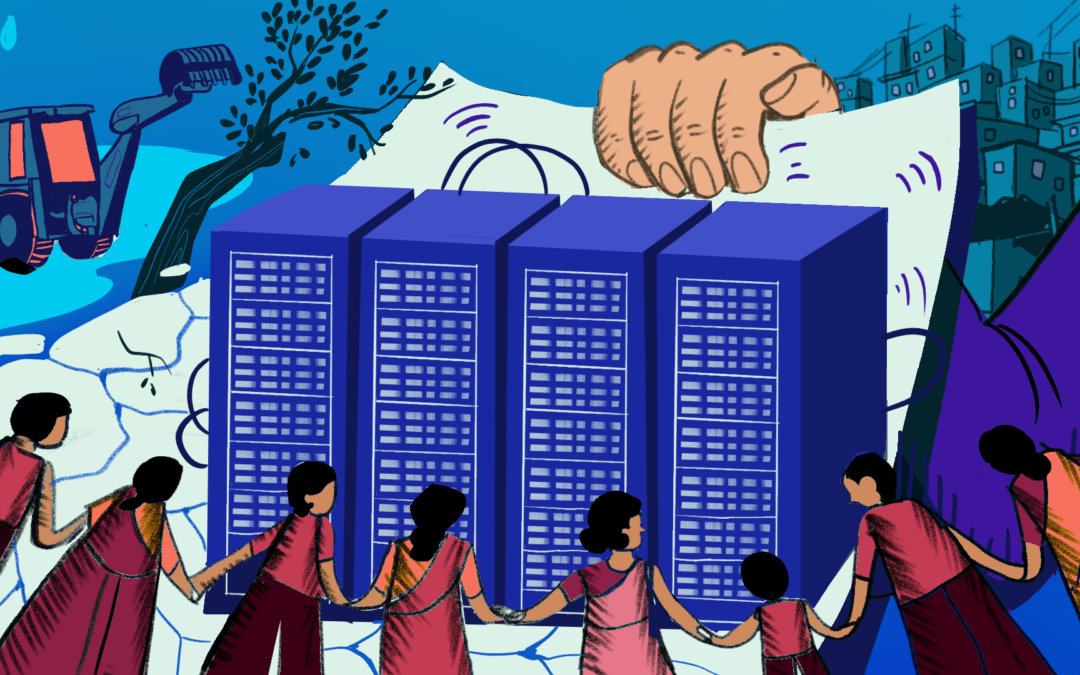
The Environmental Gamble
However, this digital infrastructure surge poses significant ecological risks:
Coal Dependency: Because data centers require uninterrupted, 24/7 power, they increase demand on India’s grid, which relies on fossil fuels for over 70% of its electricity.
Water Scarcity: Data centers consumed 150 billion liters of water in 2025. Over half of India’s facilities are located in water-stressed regions.
Grid and Urban Strain: High-density AI workloads draw intense power, exacerbating urban heat island effects and overloading local substations.
While operators are piloting solar-wind hybrids and liquid cooling, a policy gap remains. India’s regulatory frameworks currently lack binding mandates for renewable energy procurement, water usage effectiveness (WUE), and resource-conscious spatial planning. Balancing this immense economic engine with environmental sustainability is India’s next critical challenge.
India’s Data Center Boom: Economic Windfall or Environmental Gamble?
Recent Comments